October brings warmer weather, longer days, and new spring growth. It’s a fresh chance to check in, take stock and prepare for the final stretch of the year.
The continuing concerns over inflation prompted the Reserve Bank to lift the cash rate by 0.25% to 4.6%, the highest level in 15 years. The RBA says that rising energy costs and stronger than expected economic activity also contributed to the decision.
Inflation remained above the RBA’s target range, with CPI surging to 4.0%, while the trimmed mean remained steady at 3.6%.
Consumer confidence declined 5.2% to 84.4 in September, down from 88.9 in August. This reflects concerns about cost-of-living pressures, higher interest rates and continued global uncertainty.
Australian share markets were weaker during the month with the S&P/ASX 200 retreating from the 9,000-point level as rising bond yields and expectations of higher interest rates took a toll on investor sentiment.
Oil prices remained high and volatile climbing back over US$100 a barrel, while the Australian dollar eased back towards US70 cents by month’s end.
 Signals from the bond markets
If the financial markets could talk, then bonds would probably be saying: “We’re not convinced the story is over yet”.
Bond yields have been rising around the world as investors reassess the outlook for inflation, economic growth and government borrowing. The moves have been significant enough to influence mortgage rates, government finances and investment portfolios.
Experienced bond investors will be well aware of what’s been happening. For everyone else, the developments offer the chance to understand why professional investors see the bond market as one of the economy’s most important barometers.
You might never have bought a bond, researched a bond ETF or checked the yield on a government bond. But there’s a good chance that bonds already play a role in your investment portfolio through your superannuation account.
That’s one reason the recent attention on bond markets matters.
Looking back
From the early 1980s to around 2020, developed economies experienced one of the longest declines in interest rates and bond yields in modern history. Falling inflation, globalisation, technological advances and relatively stable economic conditions helped drive yields steadily lower.
Following the Global Financial Crisis and then the COVID-19 pandemic, many government bond yields fell to historically low levels. In some countries, investors were even willing to accept negative yields.
That changed dramatically from 2022 onwards as inflation surged. Central banks, including the Reserve Bank of Australia, responded by rapidly increasing interest rates.
The rapid increase in yields created short-term pain for existing bond investors but ultimately restored something that had been largely missing from bond markets for years: meaningful income.
Today, many commentators believe the era of ultra-low bond yields may be over. While inflation has eased from its peak, investors are increasingly questioning whether interest rates will return to the unusually low levels that prevailed during the 2010s.i
What’s happening in Australia?
Australian bond yields have moved higher during 2026 as investors responded to stronger than expected inflation and economic activity, and commentators are not confident that inflation will return quickly to the Reserve Bank’s target range.
Three-year government bond yields moved above 5 per cent, while 10-year bond yields approached levels not seen for more than a decade.ii
Higher yields affect far more than investment portfolios. Governments face increased borrowing costs, businesses pay more to raise capital, and lending rates throughout the economy may come under upward pressure.
The global picture
But Australia is not alone. Across the world, governments are issuing large amounts of debt to fund spending commitments, infrastructure projects and budget deficits.
Earlier this year, the International Monetary Fund (IMF) warned about the risks of geopolitical tensions, inflation uncertainty and rising levels of government debt.
Meanwhile, BlackRock notes that government borrowing is increasingly competing with private-sector demand for capital, helping push long-term yields higher in many countries. Its investment team believes that higher yields have created attractive income opportunities, but investors need to be more selective than in the past.
Understanding duration
‘Duration’ is one of the most important concepts in bond investing.
It measures how sensitive a bond’s price is to changes in interest rates. Generally speaking, the longer a bond’s duration, the more its price will move when rates change.
For example, a 10-year bond will usually experience greater price movements than a two-year bond if market interest rates rise or fall.
That helps explain why some bonds can experience significant short-term losses even when the issuer is considered financially secure. Investors often focus on credit risk, but interest-rate risk can be just as important.
The sharp rise in global yields over recent years has highlighted the importance of duration. Longer-dated bonds, which benefited hugely when rates were falling, were among the hardest hit when yields moved higher.
The bottom line
After years of being overlooked, bonds are once again demanding investors’ attention with higher yields providing more income than for much of the last decade.
At the same time, the rising yields are a reminder that bonds are not risk-free and that issues such as duration, inflation and government borrowing matter.
Although forecasts differ on the precise direction of interest rates, there appears to be broad agreement that investors should prepare for a more complex bond market.
i Fixed Income & Bond Market Outlook | BlackRock
ii Rising bond yields are punching a $10 billion hole in Australian government budgets | AFR
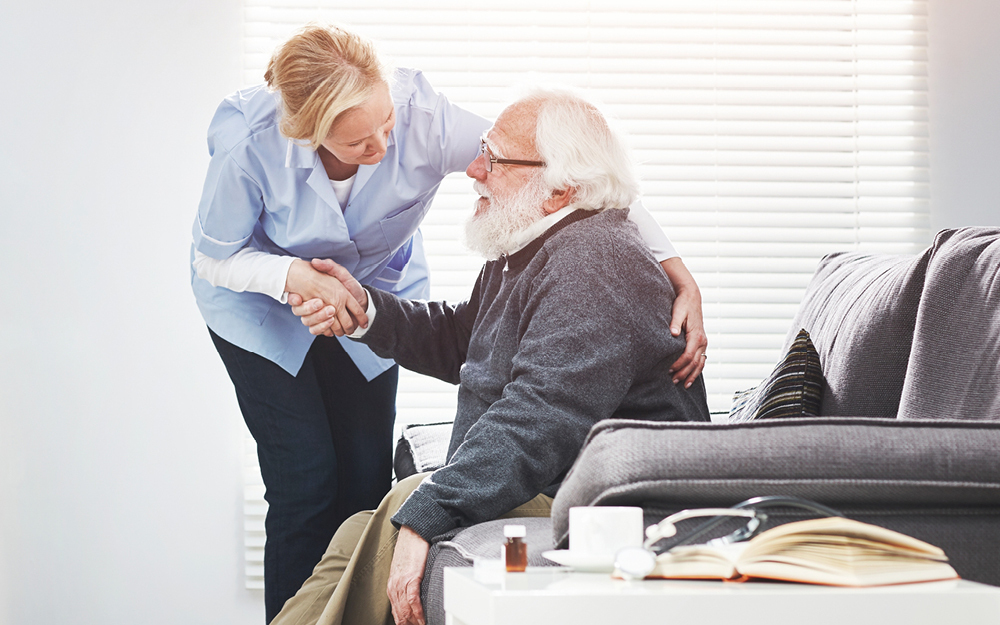 The new aged care reality
One year after the introduction of the new Aged Care Act, older Australians and their families are adjusting to a changed aged care landscape that includes new funding arrangements, higher costs for new entrants and ongoing service demand.
Most of us want to remain living at home and be independent for as long as possible and the Support at Home program is designed to do just that. This program replaced the Home Care Package and is the main way individuals could receive government aged care subsidies to remain at home for longer.
However, there is an incremental waiting list and demand for the eight levels of funding under Support at Home is continuing to exceed the places that are available. As a result, most people are relying on the less robust Commonwealth Home Support Program (CHSP) for subsidised help or they are paying for help privately.
Thankfully, the CHSP entry level aged care funding currently being used by about 850,000 Australians, which was to be wound up in July 2027, has been extended to July 2029 while the government determines how this program can continue to support the community in the longer-term.
For many, it remains a cheaper option for the limited services such as domestic help and social support that many people need to remain at home.
Support at Home
Support at Home has higher home care package budgets that range from $11,000 to $80,000 a year, which recipients may need to contribute to depending on their income as well as the services they choose.
Those with Support at Home packages can choose government-approved services from three categories: clinical care (such as nursing and personal care); independence support (such as transport and social support) and everyday living services (such as gardening, meal preparation and cleaning).
Clinical care is fully funded by the Government (which now includes personal care) but the other categories may require client contributions as shown in the table.
The Extra financial support was also introduced on 1 November 2025 and available to approved recipients for:
Restorative care: Provides up to $6,000 or $12,000 for intensive nursing support over 16 weeks.
Assistive technology and home modifications: Provides upfront access to approved equipment, products, and home modifications based on assessed needs, without requiring participants to save funds from their standard package.
End-of-life care services at home: Provides around $25,000 in short-term support during the final months of life.i
Support at Home client contributions based on service
|
|
Client contribution: % of cost |
||
|
Clinical Care: personal care, nursing, allied health |
Independence Support: social support and transport |
Everyday living: domestic help and meals |
|
|
Full (means tested) pensioner |
0% |
5% |
17.5% |
|
Part pensioner and Commonwealth Senior Health Card Holder |
0% |
5-50% |
17.5-80% |
|
Self-funded or not means tested |
0% |
50% |
80% |
Residential care
Australians are living longer and demand for suitable home care services continues to put pressure on residential aged care.
To help aged care providers access funds to build more aged care rooms, there is now a 2 per cent a year retention fee on the Refundable Accommodation Deposit paid. The fee is capped at 10 per cent.
Residents can still opt to ‘rent a room’ and pay a Daily Accommodation Payment, however the cost goes up every six months in line with inflation.
The other fees now applicable to new residents with assets above the minimum thresholds are: the basic daily fee (set at 85 per cent of the single age pension); a hotelling contribution and a non-clinical care contribution.
An increasing number of facilities are also charging a higher everyday living fee (previously known as extra or additional services) and it covers things like a television in the room, hot breakfasts, clothes labelling and weekly high tea.
The annual cap on means tested care fees no longer exists but there is a lifetime cap on the non-clinical care contribution (and the income tested contributions to support at home services) of about $137,000 a year (indexed).
Seeking advice
Navigating aged care is very complex and financial advice can help you or a family member understand your current financial position well before you need to access aged care. We can help to reduce stress on the family, so you can make a considered decisions to suit financial, lifestyle and care needs.
 Mastering AI: it’s all in the prompts
It’s impossible to miss the buzz around Artificial Intelligence (AI). It’s changing the way we work and live – but if you haven’t yet started dabbling in it, it might seem a little intimidating.
The language sounds technical, the tools look unfamiliar, and the speed at which everything is evolving can make it seem as though you are already behind. It is completely reasonable to feel hesitant or avoid the platforms that use AI altogether.
However, if you are not using AI, you might be in the minority. The statistics show that roughly 66 per cent of people globally use AI regularly and that figure is growing all the time, so it might be worth overcoming your reticence.i
The truth is you do not need to have an in depth understanding of how AI works in order to use it well. At its core, AI responds to conversation. If you can explain a situation, describe a goal, or ask questions, you already have the skill that matters most.
Turn overwhelm into order
One of the most immediate ways AI can improve your life is by helping you organise your thinking when everything feels scattered. When your to do list feels endless and your priorities become a blur, it becomes difficult to get started.
For example, you might write:
“Here is everything on my mind this week. Turn this into a prioritised action plan for the next three days, highlighting what is urgent and what can wait.”
Seeing your responsibilities organised clearly often creates immediate relief. What felt chaotic becomes sequenced. And when you know what to focus on first, it becomes easier to begin.
Accelerate the way you learn
Learning something new often feels slow, not because it is too difficult, but because it lacks structure. Without a clear starting point, it is easy to consume random information and still feel unsure about what truly matters.
AI can help you create that structure. You might prompt:
“Create a simple 30-day roadmap to help me become competent in [skill]. Focus on fundamentals first and tell me what I can ignore at the beginning.”
That final sentence is powerful. Knowing what not to focus on prevents distraction. Instead of wandering through endless content, you follow a deliberate path.
Make decisions with greater clarity
Decision making becomes stressful when emotion clouds judgment, especially when the outcome feels important. In those moments, laying out the situation clearly and asking for a structured breakdown of potential risks, trade-offs, and implications can create valuable distance.
You could say:
“I am deciding between Option A and Option B. Break down the pros, cons, risks, and likely long-term implications of each.”
The goal is not to hand over responsibility, but to organise your thinking. Once trade-offs are laid out clearly, the right direction often feels less overwhelming.
Strengthen your thinking before you act
Another powerful way to use AI is to invite it to challenge your plans before the real world does. By asking where your strategy might fail or what assumptions you could be overlooking, you move from hopeful thinking to resilient thinking.
Try a simple prompt such as:
“Critique this plan. Where could it fail? What assumptions am I making?”
This can reveal blind spots you may not have considered. Identifying weaknesses early allows you to refine your approach while the stakes are still manageable.
Build systems that reduce mental strain
Many people rely on motivation to carry them toward their goals, yet motivation is unpredictable. AI can help you design simple, repeatable systems that remove the need to constantly decide what to do next.
For example:
“Design a simple weekly system that ensures I consistently make progress toward [goal], with clear actions and checkpoints.”
Instead of relying on how you feel each day, you follow a rhythm. Over time, small consistent actions compound into meaningful results.
The real shift
New tools often appear complex until we realise how simply they can be used.
When approached as a thinking partner rather than a technical system, AI becomes less about innovation and more about clarity. You do not need to be highly technical. You just need curiosity and a willingness to ask thoughtful questions – and be open to where the answers take you.